

The status of world economies varies from country to country. Rich nations typically enjoy flourishing economies, whereas poorer nations struggle to meet basic needs. Recession has no doubt dented the economies of rich nations as well, but under normal conditions, well-to-do countries such as the US enjoy a higher standard of living than developing or underdeveloped countries.
Editor’s note (updated November 2026): The original article below was written in 2009, in the middle of the global financial crisis. We have kept it unchanged as historical context. Words such as “the present recession” refer to 2008-09, not today. New sections add current figures from the IMF World Economic Outlook, October 2026 and the World Bank Global Economic Prospects, June 2026, so you can see how the world economy then compares with the world economy now.
What’s the world economy scenario?
The world economy grew by about 5.2% in 2007: China (11%), Russia (8%), India (9%). The world economy looked quite good at the beginning of 2007. Of course, the global economy also faced the risk of 1970s-style stagflation.
At the beginning of the 1970s, the emerging global markets of China, Russia, India, and Brazil (the BRIC countries) had been showing a growth rate of 7% to 10% for several years. Property and stock market booms brought much prosperity to North America and Europe. In the Middle East and Africa, much investment was underway, and Japan was also recovering from its deflationary phase.
Developed and developing countries depended on the well-being of developed nations. Now Asian countries such as China and India are also trying to make it on their own steam. No doubt, their large population is holding them back from progressing well.
How does a recession affect the global economy?
The present recession has left both the developed and developing countries in the lurch. The US, otherwise a prosperous nation, is facing a financial crisis with rampant unemployment. Federal funds are being diverted to rescue banks and companies suffering from heavy losses. This has not been appreciated by taxpayers at all.
The recession in the US has also affected other economies worldwide, particularly developing ones such as India. Here also, banks are not supplying loans to investors, thus affecting investment. Unemployment is very high. People have just been laid off or are settling for lower salaries.
Mortgage holders in the US are facing a serious financial crunch and are faced with negative equity.
2008-09 crisis vs current economy: what has changed
The section above describes the 2008-09 downturn as it was unfolding. If you want the basics first, see what an economic recession is and how it differs from a depression. The table below sets that historical episode against the economy of late 2026.
| Factor | 2008-09 crisis (historical context) | Current economy (2025-26) |
|---|---|---|
| What triggered it | The US housing and mortgage bust spread through the banking system. Lehman Brothers collapsed in September 2008. | An energy price shock linked to the Middle East conflict and disruption in the Strait of Hormuz, along with high public debt and rising borrowing costs, according to the IMF World Economic Outlook, October 2026. |
| World growth | World output shrank in 2009 (about -0.1% on IMF purchasing-power weights), the first annual fall in decades (IMF DataMapper). | Growth is slowing, but the economy is not shrinking. The IMF expects 3.1% in 2026. The World Bank, using market exchange rates, expects 2.5%, its weakest reading since the pandemic. |
| US unemployment | Peaked at 10.0% in October 2009 (BLS data via FRED). | 4.1% in October 2026 (BLS Employment Situation, 6 November 2026). |
| Prices and oil | Oil spiked to nearly $147 a barrel in July 2008, then collapsed as demand fell. Inflation dropped sharply in 2009. | The IMF assumes oil averages about $96 a barrel in 2026 and expects world inflation to rise to 4.7% this year before easing to 4.1% in 2027. |
| Interest rates | The US Federal Reserve cut its policy rate to a range of 0 to 0.25% in December 2008 (Federal Reserve). | Central banks went through the sharpest tightening in about half a century after 2022. With inflation rising again, they have less room to cut than in 2008. |
| Banks | The banking system was the centre of the crisis, and governments had to rescue lenders. | The IMF says the financial system has broadly withstood repeated shocks. The pressure now falls more on government budgets and on energy importers. |
The short version: 2008-09 was a banking crisis that crushed demand, so prices fell. Today’s slowdown is a supply shock that pushes prices up while growth softens. That mix sits closer to the stagflation risk the original article warned about. For lessons from the earlier crash, read recession: a lesson to be learnt and can recession be forgotten?
Rise in prices
Inflation has affected many economies. Oil prices have gone up, and the prices of essential commodities have also risen. The developing economies are definitely finding it difficult to feed their millions. Rice and food grains have doubled between 2007 and 2008.
Now, in India, the rains have failed this year, adding fuel to the fire. Farmers face an acute water shortage and cannot grow their crops. Naturally, food prices have shot up. Many live below the poverty level and are unable to have a square meal a day. These setbacks further affect their living standards, which is very pathetic.
The world economy today: US, China, India and the Eurozone
The original article compared rich and developing nations in 2009. Here is how four of the largest economies look now. Actual figures and IMF forecasts are kept in separate parts of the table so you can tell what has happened from what is expected.
| Indicator | US | China | India | Eurozone |
|---|---|---|---|---|
| Actual (latest reported) | ||||
| GDP growth, 2025 | 2.1% (BEA) | 5.0% (NBS) | 7.8% (fiscal year 2025-26) | 1.2% |
| Inflation, 2025 | 2.7% | 0.0% (NBS) | 2.0% (fiscal year 2025-26) | 2.1% |
| Unemployment, latest month | 4.1% (October 2026, BLS) | 5.2% urban surveyed rate (September 2026, NBS) | 5.0% (September 2026, PLFS monthly bulletin, age 15+) | 6.5% (September 2026, Eurostat) |
| IMF forecast (World Economic Outlook, October 2026) | ||||
| GDP growth, 2026 | 2.3% | 4.5% | 7.0% (fiscal year) | 1.1% |
| GDP growth, 2027 | 2.3% | 4.0% | 7.0% (fiscal year) | 1.2% |
| Inflation, 2026 | 3.6% | Not given in IMF summary | 5.0% (fiscal year) | 3.1% |
| Inflation, 2027 | 2.8% | Not given in IMF summary | 4.4% (fiscal year) | 2.8% |
Notes: Unless stated, figures come from the IMF World Economic Outlook, October 2026. India’s data follow its April to March fiscal year, so “2025” means 2025-26. Unemployment is measured differently in each economy (China covers urban areas only, and India uses the current weekly status method), so compare trends rather than levels.
Three things stand out. India remains the fastest-growing large economy, though inflation there is expected to jump from a very low base. China is growing more slowly as weak household spending and a strained property market weigh on demand, a theme we explored in will China and India prove better than the West? The US and Eurozone are growing modestly, but both face a fresh rise in inflation driven by energy. The gap between fast and slow economies, which the original article called lopsided development, has not closed. Our piece on why some nations are rich looks at the deeper reasons.
Five-year trend: world growth and inflation
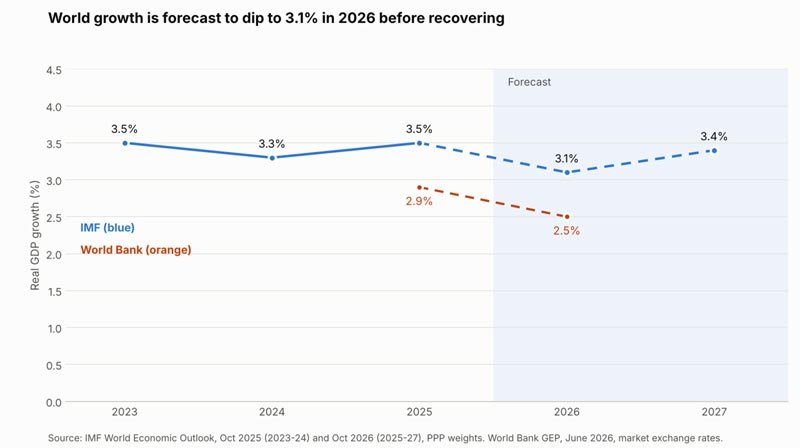
Growth has held around 3.3% to 3.5% for three years. The IMF expects a dip to 3.1% in 2026 and a partial recovery in 2027, assuming shipping through the Strait of Hormuz returns to normal from March 2027. The World Bank is gloomier. In June 2026 it said about two-thirds of economies had their forecasts cut, and it warned growth could fall to 1.3% in a downside scenario.
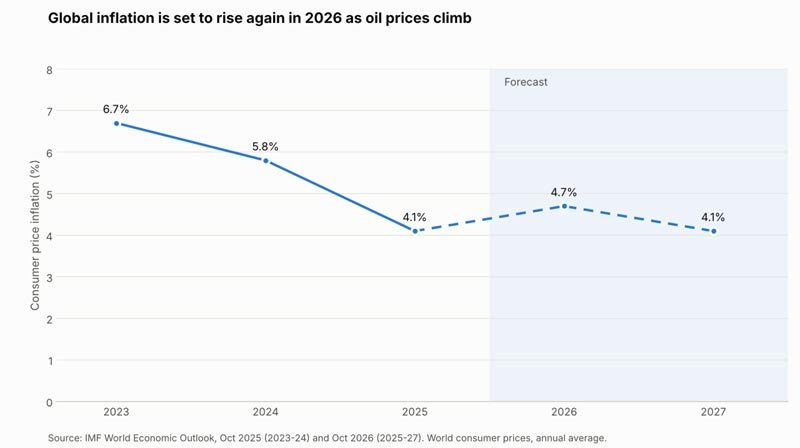
Inflation had been falling steadily from its 2023 high until the energy shock reversed the trend this year. The IMF expects inflation of about 5.7% in emerging and developing economies in 2026, against 3.1% in advanced economies, so poorer countries are feeling the price rise most. That echoes the original article’s point that developing economies find it hardest to feed their millions when prices rise.
Rise in unemployment
Presently, due to the recession, even developed countries are facing unemployment. Developing economies have long faced unemployment due to their overpopulation and lack of proper technology to tap natural resources to their maximum.
Stagflation Era
Stagflation refers to a condition whereby inflation coexists with economic stagnation. There are less growth opportunities. Prices continue to increase with less supply of commodities. Economists say the present era is a stagflation era. The 1970s faced such a situation.
Demand has been increasing, and some are concerned that the Earth’s resources are reaching a state of depletion. The view is that more investment in renewable energy is needed to avert stagflation.
Lopsided Development
Rich nations are getting richer, while poorer nations suffer from severe malnutrition and poverty. World bodies try to help these poorer nations financially, yet the problem remains unresolved. War, internal strife, and extremist activities are keeping nations apart. A global world has yet to emerge. White racial superiority persists, although US President Obama’s election indicates that there is a growing trend towards anti-racism.
The world now faces an economic crisis. It is better to realize that we must conserve natural resources and avoid extravagant spending. The gap between the rich and the poor nations must be bridged. Unnecessary spending should be avoided. Yet recession is a temporary phase. Once it is over people will return to their normal spending habits.
What this means for households and businesses
Global forecasts can feel distant, but they show up in grocery bills, loan statements and job offers. Here is how the current outlook affects everyday decisions.
Prices
Energy is the main driver this time. Higher oil prices feed into fuel, transport and food costs, and the IMF has raised its 2026 inflation forecast largely for that reason. For households, the practical step is to review fixed costs such as fuel, electricity and subscriptions first, because they add up every month. Our guides on balancing the budget during a recession and saving pennies during a downturn still apply. Businesses that depend on fuel or imported inputs should check how much of a cost rise they can pass on to customers before margins shrink.
Borrowing
Unlike 2008, when central banks slashed rates to near zero, rising inflation makes quick rate cuts less likely now. Loans are likely to stay relatively expensive. If you have floating-rate debt, work out what your repayment would be if rates stayed where they are for another year. Keep an emergency fund in an account that pays a decent rate; in India, our list of top banks for savings accounts can help you compare. Small firms should avoid planning expansion on the assumption that credit will get cheaper soon, and should read up on the major risk factors an entrepreneur faces, cash flow above all.
Jobs
Labour markets are softer than a year ago but far from 2009 levels. US unemployment is 4.1%, compared with a 10% peak during the financial crisis. The Eurozone rate has crept up to its highest level since early 2024, and in India, unemployment among urban youth aged 15 to 29 reached 19% in September 2026, according to the PLFS bulletin. If your sector is exposed to energy costs or exports, now is a good time to update your skills rather than waiting for a layoff. If you have already lost a job, our article on dealing with unemployment offers practical steps. Employers cutting costs can read how to handle layoffs and keep remaining staff engaged.
A quick checklist
- Households: build or top up three to six months of essential expenses in savings, cut recurring costs first, and avoid taking on new variable-rate debt.
- Businesses: stress-test cash flow for higher fuel and borrowing costs, look for second suppliers for key inputs, and be wary of over-relying on a single export market (see the advantages and disadvantages of international trade).
- Everyone: watch the next IMF update in January 2027 and your central bank’s rate decisions, as these will show whether the 2026 slowdown is easing.
Frequently asked questions
Is the world in a recession now?
No. Global growth is slowing but still positive. The IMF forecasts 3.1% for 2026 and the World Bank 2.5%. In 2009, by contrast, world output actually shrank.
How is the current slowdown different from 2008-09?
The 2008-09 crisis began in banks and caused prices to fall. The current slowdown began with an energy shock and is pushing prices up, which limits how far central banks can cut rates.
Which major economy is growing fastest?
India. The IMF expects about 7% growth in fiscal years 2026-27 and 2027-28, ahead of China’s 4.5% forecast for 2026.
Will prices keep rising?
The IMF expects world inflation to peak at 4.7% in 2026 and ease to 4.1% in 2027. That forecast depends on oil prices falling as shipping routes reopen, so it could change if the energy shock lasts longer.

I am an African.the continent is swimming in poverty.